Why Title Work Matters More Than Ever

Risk, Fraud, and the Real Value Behind Every Closing

In today’s real estate environment, the closing table is more than a final step—it’s a critical checkpoint in a transaction filled with legal, financial, and cybersecurity risk.

And those risks are not hypothetical. They are measurable, costly, and increasing.


Fraud Is Real—and Expensive
Cybersecurity

Real estate fraud continues to be one of the most serious threats in a transaction.

According to the American Land Title Association (ALTA), fraud and forgery claims represent approximately 21% of total title insurance claim costs, with the average claim exceeding $143,000. Refinance-related fraud claims are even higher, averaging more than $200,000 per claim.


At the same time, cybercrime is accelerating. The Federal Bureau of Investigation reports that business email compromise (BEC)—a common tactic used in real estate wire fraud—contributed to billions of dollars in losses annually, with total cybercrime losses reaching $16.6 billion in 2024.

Most fraud doesn’t start at the closing table. It starts in your inbox.


Title Work Is Risk Prevention—Not Paperwork
Risk Management

One of the biggest misconceptions in real estate is that title work is administrative.

In reality, it is one of the most important forms of risk prevention in the entire transaction.

ALTA reports that the title industry helps mitigate between $600 billion and $900 billion in potential risk exposure annually, with that number exceeding $1 trillion during peak market periods.


Additionally, nearly 30% of title claims involve issues that are not discoverable through public records alone. This means many of the most serious risks require professional expertise to identify and resolve.

These issues can include:
Unknown heirs
Forged or improperly recorded documents
Undisclosed liens
Errors in legal descriptions

Many of the most costly problems are invisible without expert review.


Claims Data Reinforces the Need for Protection
Data protection


Title insurance is not theoretical. It is backed by real claims activity.

ALTA reports that the industry paid more than $336 million in claims in the first half of 2025 alone, demonstrating the ongoing need for protection against title defects and fraud.


This is what title insurance is designed to do:
Identify issues before closing
Resolve them whenever possible
Protect property owners and lenders when issues arise


Cybersecurity Is Now Part of Every Closing
Secure file with padlock


ALTA’s Cybercrime and Wire Fraud Study found that:
Over 90% of title companies report cyberattack attempts are increasing or staying the same
Nearly 60% have experienced attempted fraud, including wire fraud and business email compromise


These findings reinforce an important reality: Security is no longer optional. It is essential.

At Landmark Title Agency South, that means:
Verifying all wire instructions
Using secure communication protocols
Educating clients and partners on fraud prevention


A Strong Industry Backing Every Transaction
Alta Logo


The title industry remains a stable and essential part of the real estate market.


According to ALTA:

$3.9 billion in title insurance premiums were generated in Q1 2025
$4.5 billion in Q2 2025
$16.2 billion total premiums in 2024

These numbers reflect an industry built on protecting property rights and financial security. One that is supported by strong reserves and consistent claims performance.


Technology Is Advancing—But Expertise Still Leads
Data analysis

The title industry continues to evolve with digital tools and closing innovations.

ALTA reports that the number of title companies offering digital closings has increased significantly in recent years, reflecting growing demand for efficiency and convenience.

But while technology improves speed, it does not replace expertise.

Careful review by skilled staff, informed judgment, and accountability remain at the core of a secure closing.


The Landmark Difference
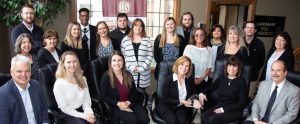
Landmark Team 2026


For buyers, sellers, lenders, and real estate professionals, the value of title work is not always visible.


It’s found in what doesn’t happen:
The fraud that is prevented
The issue that is caught early
The risk that is resolved before it becomes a problem

At Landmark Title Agency South, every closing is approached with that responsibility in mind. We combine experience, precision, and protection to ensure your transaction is not just completed, but completed with confidence.

_________________
Sources
American Land Title Association (ALTA) – Claims Analysis; Market Share & Premium Reports; Cybercrime & Wire Fraud Study
Federal Bureau of Investigation – Internet Crime Report 2024 (Business Email Compromise & Cybercrime Losses)
Read more

New FinCEN AML Real Estate Reporting Rule

New FinCEN AML Real Estate Reporting Rule Takes Effect March 1, 2026


What It Means for Certain Property Transfers and How Landmark Title Agency South Is Prepared

 Beginning March 1, 2026, a new federal Anti-Money Laundering (AML) reporting rule issued by the Financial Crimes Enforcement Network (FinCEN) will change reporting requirements for certain residential real estate transactions nationwide.

If you are a realtor, lender, buyer, seller, or investor, this is an important regulatory update to understand. The rule introduces new reporting obligations tied to specific types of property transfers. This rule applies nationwide.

At Landmark Title Agency South, we have been preparing in advance so our clients and partners can continue to close with confidence.


Why This New Rule Exists

FinCEN’s new AML real estate reporting rule is designed to increase transparency in property transfers involving legal entities and trusts that do not use traditional financing. Regulators have identified certain transaction structures as higher risk for misuse, and this rule establishes standardized federal reporting to address those risks.

While prior FinCEN Geographic Targeting Orders (GTOs) applied only to select counties and markets, this new rule creates a consistent national reporting framework.


Which Transactions May Trigger Reporting

Under the new rule, reporting may be required for certain non-financed residential real estate transfers involving:

  • Legal entities
  • Trusts
  • Structured ownership arrangements

Important clarifications:

  • “Residential real property” is defined broadly
  • Coverage may extend beyond typical 1–4 family homes
  • “Non-financed” is broader than simply “all cash”
  • Certain transaction types are exempt
  • Responsibility to report follows a defined role order among settlement participants

Not every transaction will be reportable — but some will require additional documentation and federal filing.


Reporting Deadlines and Compliance Requirements

When reporting is required, the rule establishes:

  • Specific post-closing filing deadlines
  • Required identity and transaction data collection
  • Federal record-retention standards
  • Defined responsibility based on transaction roles
  • Potential civil and criminal penalties for non-compliance

Accuracy, timing, and documentation controls are essential under the new framework.


What This Means for Realtors, Lenders, Buyers & Sellers

For most traditionally financed residential transactions, the closing process will feel very familiar.

However, for transactions that fall within the reporting scope, parties may be asked to provide additional information or verification details. These steps are designed to meet federal compliance requirements — not to delay closings — and will be handled through structured procedures.

Clear communication and early identification will be key to avoiding surprises.


How Landmark Title Agency South Is Handling the Change

Landmark Title Agency South has implemented updated compliance procedures, workflow checkpoints, and staff training to support the new FinCEN reporting requirements.

When applicable, our team will:

  • Identify reportable transactions early in the process
  • Guide parties through required information collection
  • Coordinate secure documentation handling
  • Manage reporting timelines
  • Maintain required compliance records
  • Communicate clearly with all transaction partners

Our objective is to integrate compliance into the closing process — not disrupt it.


A Trusted Closing Partner Matters More Than Ever

Regulatory requirements in real estate continue to evolve. Having an experienced, proactive title partner helps ensure transactions remain secure, compliant, and on schedule.

Landmark Title Agency South remains committed to:

  • Transaction security
  • Regulatory compliance
  • Clear communication
  • Efficient closings
  • Local expert support


Questions About the New FinCEN Rule?

If you have questions about how the March 1, 2026, FinCEN AML reporting rule may affect an upcoming transaction, our team is here to help.


Contact Landmark Title Agency South — the Landmark Team is ready.

937.432.6300 | info@landmarktitlesouth.com

Read more

Landmark Team’s CEO, Chris Cartwright, speaks on Title Fraud with Sandy Collins, iHeartCinci Podcast

Landmark Team’s CEO, Chris Cartwright, speaks on Title Fraud, an increasingly problematic problem in America. Chris was invited to discuss this pressing topic with Sandy Collins, host of iHeartCinci Podcast, after Sandy received an FBI alert on the topic.[/vc_column_text][/vc_column][/vc_row]

Read more

The Role of Title Insurance in Real Estate Transactions

The Role of Title Insurance in Real Estate Transactions

In the realm of real estate transactions, the significance of title insurance cannot be overstated. Serving as a critical safeguard against unforeseen ownership disputes and title defects, title insurance plays a pivotal role in ensuring the smooth transfer of property ownership. In our newsletter, “The Role of Title Insurance in Real Estate Transactions: Best Practices and Case Studies,” we explore the fundamental importance of title insurance, highlight best practices for its implementation, and examine real-world case studies that underscore its value in protecting stakeholders.

Understanding the Importance of Title Insurance

Title insurance serves as a shield, protecting property owners, lenders, and other stakeholders from potential risks associated with title defects, liens, encumbrances, and fraud. Unlike other forms of insurance that protect against future events, title insurance provides coverage for past occurrences that may jeopardize property ownership rights.

A comprehensive title search and examination are conducted during the underwriting process to identify any issues that may affect the property’s title. This diligent review helps to mitigate risks and ensure that the title is free and clear, providing peace of mind to all parties involved in the transaction.

Best Practices for Implementing Title Insurance

To maximize the efficacy of title insurance in real estate transactions, industry professionals should adhere to a set of best practices:

1. Thorough Due Diligence: Conduct comprehensive title searches and examinations to identify any existing or potential title defects, liens, or encumbrances.

2. Clear Communication: Maintain open and transparent communication with clients, explaining the importance of title insurance and addressing any concerns or questions they may have.

3. Customized Coverage: Tailor title insurance policies to meet the specific needs and circumstances of each transaction, considering factors such as property type, location, and intended use.

4. Risk Management Strategies: Implement proactive risk management measures to mitigate potential title-related risks, such as obtaining endorsements or conducting additional searches for specific issues.

5. Continual Education: Stay updated on industry trends, regulatory changes, and emerging risks through ongoing education and professional development.

Case Studies Illustrating the Value of Title Insurance

Real-world examples offer compelling evidence of the critical role that title insurance plays in safeguarding property rights and mitigating financial risks. Consider the following case studies:

1. The Hidden Lien: In a residential real estate transaction, the title search revealed an undisclosed mechanic’s lien against the property. Thanks to the comprehensive title insurance policy obtained by the buyer, the title company resolved the lien issue, protecting the buyer’s investment and preventing costly legal battles.

2. Boundary Dispute Resolution: A commercial property purchase was nearly derailed when a neighboring landowner claimed ownership of a portion of the property’s land. The title insurance policy provided coverage for the legal costs associated with resolving the boundary dispute, allowing the transaction to proceed smoothly.

3. Fraudulent Title Transfer: In a case of identity theft, an individual fraudulently transferred ownership of a property and attempted to sell it to an unsuspecting buyer. The title insurance company intervened, uncovering the fraudulent activity and restoring the rightful ownership to the original owner, thus preventing financial loss and legal complications.

These case studies underscore the invaluable protection afforded by title insurance in real estate transactions, highlighting its role in mitigating risks and preserving property rights.

Conclusion

As demonstrated, title insurance is a cornerstone of real estate transactions, providing essential protection against a myriad of potential risks. By adhering to best practices and leveraging the insights gleaned from real-world case studies, industry professionals can ensure the effective implementation of title insurance, safeguarding the interests of all parties involved in the transaction. Our newsletter serves as a valuable resource for navigating the complexities of title insurance and maximizing its benefits in real estate transactions.

Article published by Real University

Read more

Mapped: What You Need to Earn to Own a Home in 50 American Cities

(Source: Home Sweet Home & Visual Capitalist)

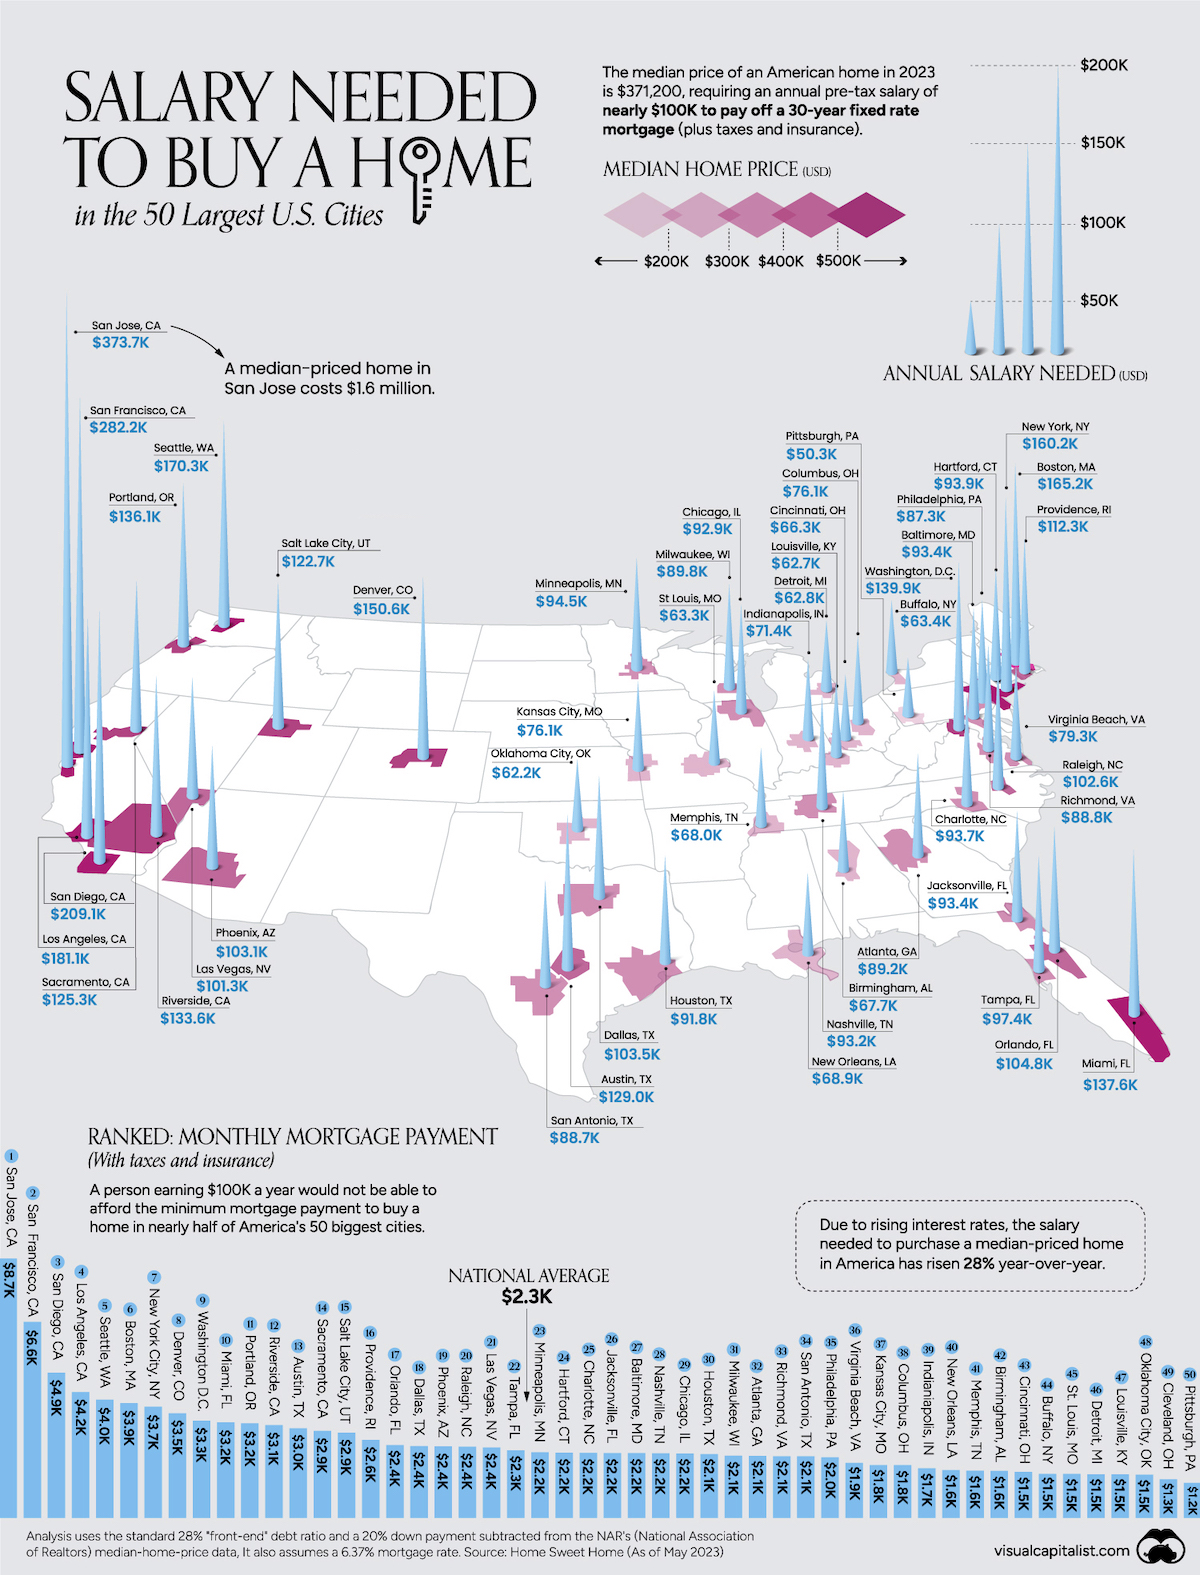
A map of the U.S. with the median home price as well as the salary needed to own a home 50 American cities.

Once a fundamental part of the American dream, the ability to own a home is drifting farther and farther away for many Americans.

Between skyrocketing prices, stagnating wages, and now rising interest rates, the deck seems to be increasingly stacked against home ownership.

Using May 2023 data tabulated by Home Sweet Home, we map out the annual salary needed to afford a 30-year mortgage (at 6.37%) to buy a home in America’s 50 most populous metropolitan areas.

The monthly minimum mortgage payment includes taxes and insurance as well, and is capped at roughly one-third of the income. This analysis also assumes that the homeowner will put down a 20% down payment.

The Least and Most Affordable American Cities to Own a Home

At the top of the list, and at the very west of the country, San Jose is the least affordable city to own a home for the average American.

One would have to earn at least $374,000 a year to afford a $1.6 million dollar home in the city.

To put those numbers into perspective, the median American annual income is $75,000, about one-fifth what’s required to buy a home in San Jose.

Other Californian cities, San Francisco (ranked 2nd), San Diego (3rd), and Los Angeles (4th) all require an annual income of at least $180,000 to attempt home ownership within their metropolitan boundaries.

Boston (ranked 6th) and New York (ranked 7th) represent unaffordability on the East Coast, both requiring at least $160,000 a year to buy homes there.

It’s not just the coasts that are expensive however. To buy a home in Denver (ranked 8th) and Salt Lake City (15th) means earning more than $120,000 a year.

However, cities in the Midwest and South, like Pittsburgh, Detroit, Oklahoma City, and Louisville, are far more affordable, requiring less than $63,000 a year to buy a home.

Interest Rates Rock Home Ownership Chances

Aside from the obvious price differences in housing markets, a key factor that has elevated income requirements across the board is the rapid rise in interest rates in the last year. In fact the average 30-year mortgage has pushed past 7%, the highest it’s been since the 2000s.

This means that while the median price of a house in San Jose has actually come down between 2022 and 2023, the minimum monthly payment has increased from $7,717 to $8,720 this year.

So to afford a median-priced home in the country, an American needs to earn closer to $100,000 a year, up from $75,500 in 2022. And even then, they would be priced out of owning a home in nearly half of the 50 largest cities in the country.

As a result Americans may yet further delay home ownership. Renting is now a far more attractive option, thanks to the biggest difference between rent and mortgages in over 50 years.

Where Does This Data Come From?

Source: Home Sweet Home (HSH).

Note: HSH used different sources for their median home prices, mortgage rate, property taxes and home insurance figures for their analysis. Please visit their website for more information.

Other: If other personal debts exceed 8% of one’s given monthly gross income, this may increase the salary needed to qualify for a mortgage.

The full story is available: What You Need to Earn to Own a Home in 50 American Cities (visualcapitalist.com)

Read more

SEXENNIAL REAPPRAISAL AND TRIENNIAL UPDATES FOR OHIO’S 88 COUNTIES | 2023-2028

SEXENNIAL REAPPRAISAL AND TRIENNIAL UPDATES FOR OHIO’S 88 COUNTIES
2023-2028

The latest sexennial reappraisal and triennial real estate tax update periods have been released for Ohio’s 88 counties from years 2023 through 2028.

2023 Reappraisal Counties

Auglaize
Clinton
Darke
Defiance
Delaware
Franklin
Gallia
Geauga
Hamilton
Hardin
Harrison
Henry
Jackson
Licking
Mahoning
Mercer
Morrow
Perry
Pickaway
Pike
Preble
Putnam
Richland
Seneca
Shelby
Trumbull
Vanwert
Wood

2024 Reappraisal Counties

Belmont
Brown
Crawford
Cuyahoga
Erie
Fayette
Highland
Huron
Jefferson
Lake
Lorain
Lucas
Morgan
Muskingum
Ottawa
Portage
Stark
Warren
Williams

2025 Reappraisal Counties

Carroll
Champaign
Clark
Fairfield
Logan
Marion
Medina
Miami
Ross
Union
Wyandot

2026 Reappraisal Counties

Ashland
Ashtabula
Athens
Butler
Clermont
Fulton
Greene
Knox
Madison
Montgomery
Noble
Summit
Wayne

2027 Reappraisal Counties

Allen
Coshocton
Guernsey
Sandusky
Vinton

2028 Reappraisal Counties

Adams
Columbiana
Hancock
Hocking
Holmes
Lawrence
Meigs
Monroe
Paulding
Scioto
Tuscarawas
Washington

2023 Update Counties

Ashland
Ashtabula
Athens
Butler
Clermont
Fulton
Greene
Knox
Madison
Montgomery
Noble
Summit
Wayne

2024 Update Counties

Allen
Coshocton
Guernsey
Sandusky
Vinton

2025 Update Counties

Adams
Columbiana
Hancock
Hocking
Holmes
Lawrence
Meigs
Monroe
Paulding
Scioto
Tuscarawas
Washington

2026 Update Counties

Auglaize
Clinton
Darke
Defiance
Delaware
Franklin
Gallia
Geauga
Hamilton
Hardin
Harrison
Henry
Jackson
Licking
Mahoning
Mercer
Morrow
Perry
Pickaway
Pike
Preble
Putnam
Richland
Seneca
Shelby
Trumbull
Vanwert
Wood

2027 Update Counties

Belmont
Brown
Crawford
Cuyahoga
Erie
Fayette
Highland
Huron
Jefferson
Lake
Lorain
Lucas
Morgan
Muskingum
Ottawa
Portage
Stark
Warren
Williams

2028 Update Counties

Carroll
Champaign
Clark
Fairfield
Logan
Marjon
Medina
Miami
Ross
Union
Wyandot

Read more

Fraud Protection

Fraud protection is essential in the title industry. Fraudulent wiring instructions have caused dramatic financial losses for title agents, realtors, homeownership, and homebuyers.

We want to keep you safe.

What we know:

    • Changes to wire instructions are not normal
    • Lender payoffs are being manipulated
    • Large losses are occurring in the industry
    • Payoff instructions are not verified

Safety Measures:

    • Question every single change to wire instructions, change requests are not normal and probably fraudulent
    • Do not reply directly to emails requesting the movement of money
    • Instead, use the “forward” option and type in the correct email address or select it from your email address book
    • Validate new payment instructions received via email—even if it is internal
    • Always verify the authenticity of each wire transfer request
    • Call, using a number you have previously called—not one from the current wire transfer request—to verify verbally
    • Verify payment instructions with any new vendor
    • Verify changes to payment instructions for an existing vendor
    • Verify pay-off account numbers before wiring funds

How can you avoid fraud?

  • Establish a verification protocol
  • Enforce the protocol with all employees
  • Re-review on a regular basis
  • Implement multi-factor authentication
Read more

Long-awaited FHA condo rules | boost to affordability


The following news is shared from an announcement by the National Association of Realtors.

HUD to announce long-awaited FHA condo rules | will give affordability a boost

The U.S. Department of Housing and Urban Development is expected to release updated guidance tomorrow on FHA-insured condominium financing. The new rules should benefit real estate clients and customers by allowing more buyers to obtain low down-payment mortgages on affordable housing options.

Specifically, the new rules will:

  • Extend FHA certifications on condo developments from two years to three years, reducing the compliance burden on condo boards.
  • Allow for single-unit mortgage approvals-often known as spot approvals-which will enable FHA insurance of individual condo units, even if the property does not have FHA approval.
  • Secure additional flexibility in the ratio of investors to owner-occupants allowed for FHA financing in a condo building.

The full guidance will go into effect in mid-October, 60 days from publication.

“Condominiums are often the most affordable option for first-time homebuyers, small families, and those in urban areas,” said NAR President John Smaby, in a statement issued to the media Wednesday morning. ‘We are thrilled that (HUD) Secretary (Ben) Carson has taken this much-needed step to put the American dream within reach for thousands of additional families.”
Since 2008, NAR has championed policy changes in condo lending. NAR has sought rules that would allow the owner-occupancy level to be determined on a case-by-case basis and that
would extend the approval period for project certification to five years.

NAR’s existing-home sales report for June showed condominium and co-op sales at a seasonally adjusted annual rate of 580,000 units, a decline of 3.3% from May and 6.5% from the same time last year. With more than 8.7 million condo units nationwide, only 17,792 FHA condo loans have been originated in the past year.

NAR Chief Economist Lawrence Yun recently noted that even though median prices for existing condos have risen slightly, their relative affordability means condominiums remain a natural answer to inventory shortages holding back home sales growth.

“Condos are typically more affordable than a detached single-family home, but only a small fraction of condos are FHA-certified,” Yun said last month.

NAR has advocated for changes to FHA’s condo policies that include allowing owner-occupancy level determination on a case-by-case basis, granting up to 45% commercial space without documentation and including a five-year approval period for project certification.

The FHA issued proposed changes to its condo rules in 2016 that would have allowed individual condo units to become eligible for FHA financing, but the proposed rules were never finalized.

HUD estimates that these new rules could cause anywhere from 20,000 to 60,000 condominium units to become eligible for FHA-insured financing annually.[/vc_column_text][/vc_column][/vc_row]

Read more

Interim Guidance for the Blue Water Navy Act of 2019

The following is excerpted from a notification from the Ohio Mortgage Bankers Association.

VA Releases Circular 26-19-23 on August 12, 2019
Circular 26-19-23, interim guidance for the Blue Water Navy Vietnam Veterans Act of 2019. Some key provisions of the Act, effective with loans closed on or after (and not before) January 1, 2020, are:

Veterans with loan amounts over $144,000, with full entitlement, will not need a down payment regardless of purchase price;

The guarantee for loans at $144,000 and less will not change;

For Veterans who have previously used entitlement that has not been restored, the maximum amount of guaranty is the lesser of 25 percent of the loan amount OR the maximum amount of guaranty entitlement available. The maximum amount of guaranty entitlement is 25 percent of the Freddie Mac Conforming Loan Limit, reduced by the amount of entitlement previously used (not restored). In other words, the loan amount without a down payment could be 4 times the remaining entitlement. 25% down payment would be required over and above that loan amount.

Funding Fees will be as follows for all veterans, regardless of whether Regular Military, Reservist, or National Guard:

Type of Loan Downpayment Percentage for First Time Use Percentage for First Time Use
Purchase and Construction Loans None
5% but less than 10%
10% or more
2.30%
1.65%
1.40%
3.60%
1.65%
1.40%
Cash-out Refinance Loans n/a 2.30% 3.60%
IRRRLS n/a 0.50% 0.50%
Loan Assumptions n/a 0.50% 0.50%

Purple Heart recipients will be exempt from paying the Funding Fee.


Read more
  • 1
  • 2
Call Now Button